








Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do Impact Windows Lower Insurance in Yorba Linda, CA?
In Florida, impact windows lower insurance premiums by a rate set in state law. In Yorba Linda, the short answer is: impact windows can lower your premium, but the bigger win in this market is staying insurable at all. Since 2020, several major carriers have non-renewed or restricted hillside policies across Orange County’s fire-risk zones. So the first question isn’t “how much will my premium drop.” It’s “will documented mitigation keep a carrier willing to write my home.” Document the upgrade correctly, with product certifications and a closed permit, and impact windows become a real underwriting asset. Call (888) 255-9354 to talk through what your carrier will recognize before you buy a single pane.

Why California’s Answer Is Harder Than Florida’s
Florida homeowners can point to a statute that assigns a defined credit for impact-rated openings. California has no equivalent statewide mandate. Carriers here weigh a mix of wildfire mitigation, brush clearance, roofing class, and windborne-debris protection, and each underwriter scores those factors differently. Two neighbors on the same Yorba Linda ridge can submit the same upgrades and get different offers.
The market context makes it worse. Hilly terrain throughout Yorba Linda means most homes sit on some grade, and carriers have grown cautious about writing or renewing policies on sloped lots near open fuel. That’s the practical reality behind the question you searched. Impact windows aren’t a magic discount button. They’re a mitigation fact you put in writing, and documented mitigation is what brings a hesitant underwriter back to the table.
What Actually Counts as “Insurance Recognized”?
A sticker that says “impact rated” isn’t the same as a certification an underwriter will accept. This is the gap that catches most Yorba Linda homeowners. A retailer’s marketing label and the product data a carrier’s inspector wants to see are two different documents.
What moves the needle in California:
- IBHS FORTIFIED and CAL FIRE Ember-Resistant Construction guidelines. Both are referenced by California carriers and the FAIR Plan when scoring a home’s mitigation history. Impact windows need to be specified against these standards, not just described as “impact.”
- AAMA 2101 or equivalent ember-intrusion ratings. The paperwork has to show the actual test standard, the glass build-up, and the frame system, in the manufacturer’s own documentation.
- Product data sheets at permit close-out. Your carrier’s inspector will want the manufacturer’s certification sheets, not your contractor’s word. Groundwork collects those sheets and hands them over so you can submit them directly.
- A closed permit record. More on that below, because it’s the part most people miss.
House Build and Fire History Change the Math Here
Yorba Linda’s housing stock matters for how a carrier reads your home. Large parts of the city built out as tract homes between the 1960s and 1980s, and a lot of those houses still carry original stucco and wood-frame construction with single-pane openings. Newer custom hillside estates sit on the same streets. Underwriters treat an older frame home on a slope near fuel differently from a newer stucco build on flat ground, and the openings are one of the few line items a homeowner can actually improve on the older homes.
The 2008 Freeway Complex fire and the burn scars it left behind still shape how carriers look at this side of the county. Combined with a semi-arid climate of hot, dry summers and rain that arrives in a few intense winter storms, the risk picture is real and local. That’s why the window upgrade carries weight here beyond wind protection.
The Permit Paper Trail Is the Part People Skip
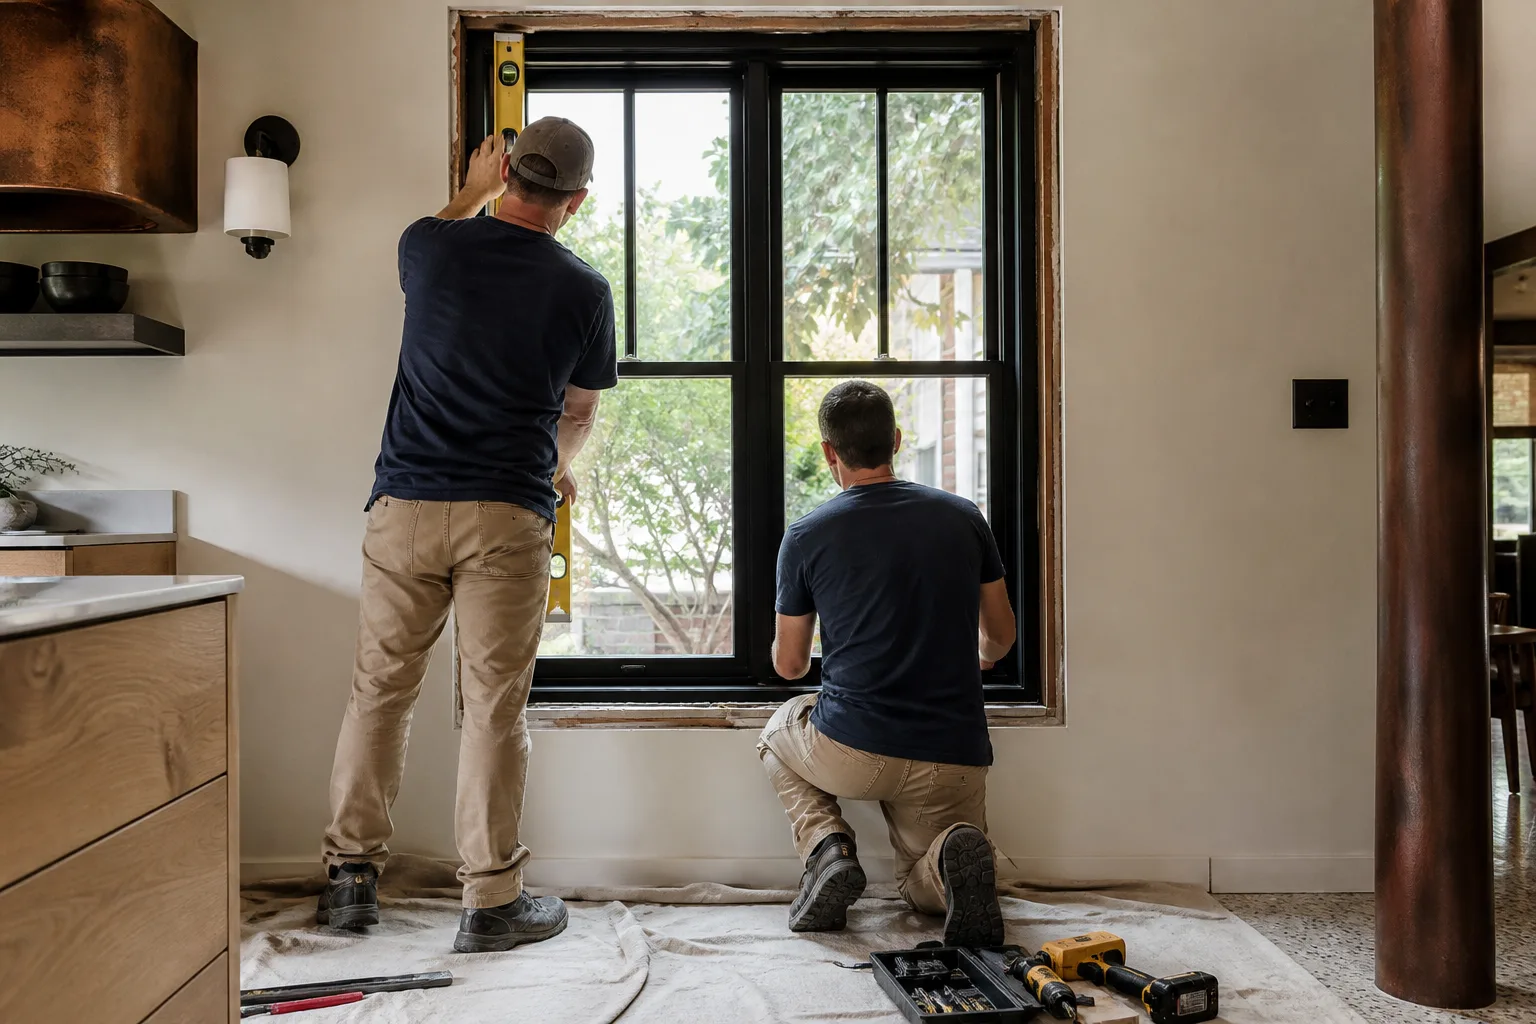
Here’s the operator detail that rarely shows up in online guides: when a window replacement is permitted, inspected, and closed by Yorba Linda’s Building Division, it creates an official record in the property file. A licensed contractor pulls the permit, the inspector signs off, and the city closes it out. That closed record lives with the address.
An unpermitted swap leaves no trace. When a carrier or a new underwriter reviews the home’s mitigation history, they’re looking at the city’s file and the manufacturer’s documents. No permit means no evidence, and no evidence means no credit. It’s that simple, and it’s the reason we never quote a window job that skips the permit. The record is half the value.
What a Yorba Linda Impact Window Job Looks Like on Paper
We specify Andersen and Marvin units with documented ratings and hand over the certification sheets you need for your carrier. Both manufacturers publish the test data underwriters accept, and the sealed units hold up in hillside conditions where wind-driven rain and ember exposure both matter. Curated brand partnerships mean you’re choosing quality rather than whatever’s in stock, and the spec gets written into the contract so there’s no ambiguity at close-out.
For hillside properties, we also look at flashing, drainage, and any slope-related details your lot demands, since a window that fails at the flashing undermines both your warranty and your mitigation file. That’s part of the Windows & Doors scope: spec the product, document it, install it so the record holds up.
Impact Window Pricing in Yorba Linda
| Scope | Typical Range |
|---|---|
| Impact window installation (full home) | $8,000-$25,000 |
| Standard window replacement | $4,500-$15,000 |
Those are honest Yorba Linda ranges for a permitted job with documented product data. If you’re also weighing a roof or an addition, a bundled project can make the financing math work harder for you. Groundwork offers a no-hassle upfront price, 0% financing for 18 months, and $1,000 off projects over $10,000. The number you see is the number you pay.
The 730-Day Done Right Promise Protects the Paperwork
Insurance documentation is only worth something if the installation stays intact. If a carrier sends an inspector and finds a failed seal or a flashing issue, your mitigation file weakens and your claim gets complicated. Our 730-Day Done Right Promise means the work is covered for two years: if it’s not done right, we make it right. It’s one of the longest workmanship guarantees in the residential construction space, and it protects both the warranty and the insurance record you filed. Technicians are background-checked and arrive in uniform, and our team has up to 12 years of experience per technician. Calls reach a live person 24/7, so if something comes up after inspection, you’re not leaving a voicemail.
Frequently Asked Questions
They can, but the amount varies by carrier and isn’t set by state law the way it is in Florida. Some California carriers offer a credit for documented impact-rated openings that meet recognized standards, while others weigh wildfire mitigation more heavily than wind. The upgrade helps most when it’s spelled out in writing and submitted with the manufacturer’s certification sheets. Call (888) 255-9354 and we’ll walk you through what to assemble before you submit to your carrier. Estimates are free.
Documented mitigation is often what gets a carrier back to the table, but there’s no guarantee any single upgrade reverses a non-renewal. What helps is a complete file: sealed permit, product certification sheets, and a clear mitigation record. That’s the difference between a homeowner saying “I put in impact windows” and handing an underwriter evidence they can score. We can help you build that file, and our Yorba Linda service area page covers how we handle hillside permits. Call (888) 255-9354 for a no-pressure assessment.
Keep the closed permit from Yorba Linda’s Building Division, the manufacturer’s product data sheets showing the AAMA 2101 or equivalent rating, the glass and frame specs, and your invoice. Those four items are what an underwriter’s inspector will ask for. Groundwork provides the certification sheets at close-out so nothing gets lost. We also stand behind the install for 730 days, so if the inspector flags anything, we fix it. Call (888) 255-9354 to get started.
That depends on whether your carrier is asking for proof of mitigation. If the windows are original single-pane from a 1970s tract build and your policy is under review, replacement usually does more for your insurability than it costs. If your carrier isn’t asking, a standard replacement range of $4,500-$15,000 may be the smarter spend, and impact units at $8,000-$25,000 can wait. Either way, get a written price before you decide. Call (888) 255-9354 and we’ll give you straight numbers on both options.
Talk to a Live Person Before Your Next Policy Review
If you’d rather have it looked at, Groundwork Construction Co. of Yorba Linda offers a no-pressure assessment in Yorba Linda. We’ll spec the windows, document the ratings, and hand you the paperwork your carrier needs. If you’ve been burned before by vague bids, our upfront pricing and 730-Day Done Right Promise back the whole job in writing. Call (888) 255-9354 today for a free estimate.
Written by the team at Groundwork Construction Co. of Yorba Linda, serving Yorba Linda, CA.


